Grow it.Guard it.Pass it on.
KELD designs Indexed Universal Life strategies and annuities that let your money ride market upside, sit out the downturns, and protect the people you love — built one family at a time by Klubo Adams.
Participate in the climb. Skip the fall.
Indexed Universal Life is permanent life insurance with a cash value that grows with an index — without being invested directly in the market. Good years are credited up to a cap. Bad years credit zero, not a loss.
Illustration only. Not a projection of any specific product. Caps, participation rates and fees vary by carrier and policy.
Upside, linked
Cash value earns interest tied to an index like the S&P 500 — up to a cap set by the carrier.
A 0% floor
When the index falls, credited interest bottoms out at zero. Prior gains stay locked in.
Tax-advantaged access
Under IRC §7702, properly structured policy loans can provide income without triggering income tax.
Living benefits
Many policies let you tap the death benefit early for qualifying chronic, critical or terminal illness.
IUL vs. 401(k): what you keep.
Move the sliders. See how a 0% floor and tax-free policy loans can change your income in retirement.
30 years of contributions · $180,000 total
About $1,301 more per year to spend with the IUL — and in the worst year your 401(k) dropped $73,148. The IUL lost $0 to the market.
Hypothetical example for education only, not a projection or offer. It assumes the same repeating 10-year index pattern for both accounts, a 10% cap and 0% floor for the IUL, about 1% yearly policy costs, 0.5% yearly 401(k) fees, and a 4.5% yearly withdrawal. It ignores employer match, insurance costs by age and health, and loan interest. Real results vary by carrier, policy design and market conditions. Ask Klubo for a licensed illustration.
One advisor. Every layer of protection.
Shopped across top-rated carriers and fitted to your age, health and goals — not a one-size product.
Is an IUL right for you? 60 seconds.
Four quick questions. Then Klubo builds a personalized IUL strategy — and you choose when to talk it through.
What do you want your money to do?
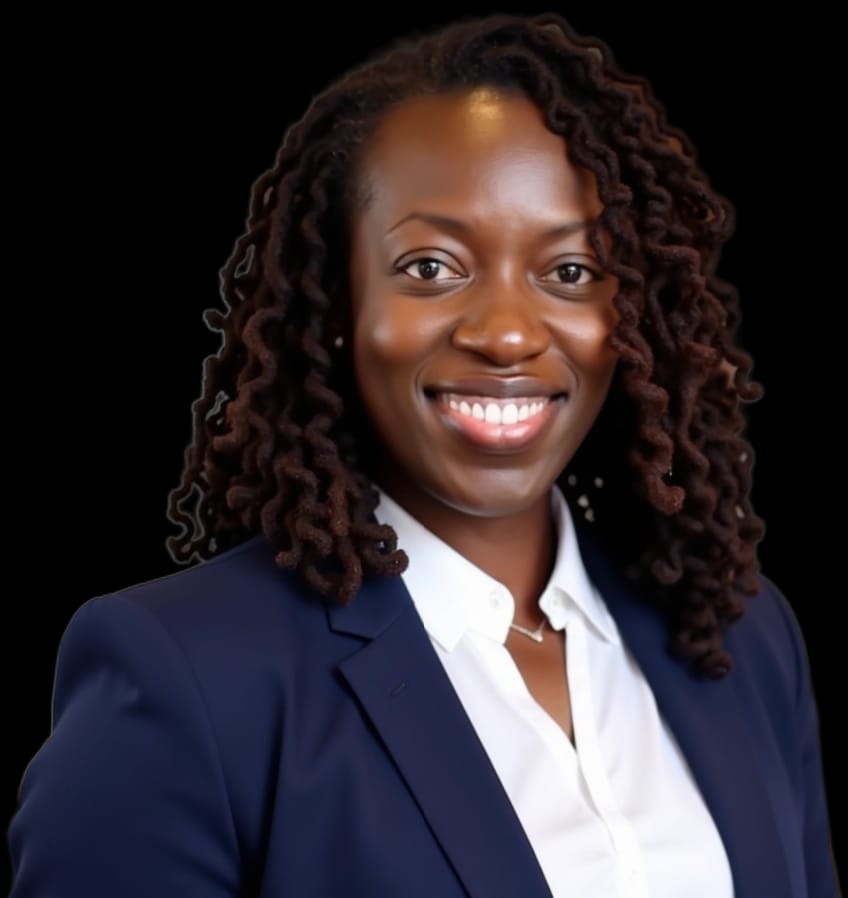
“I don't sell policies. I design blueprints — so your money works as hard as you do, and your family is never left guessing.”
Young families
Lock in low rates now and build a cash reserve as your kids grow.
High earners
Maxed out your 401(k)? Add a tax-advantaged bucket with downside protection.
Pre-retirees
Convert savings into guaranteed income with a fixed indexed annuity.
Business owners
Fund buy-sell agreements and protect key people.